Blogs

Post-Production Deductions Explained: Why Your Royalty Check May Be Smaller Than Expected
A royalty statement can look right at first glance and still leave a mineral owner with one big question: Why is the check smaller than I expected? The well produced. The commodity price looks reasonable. The ownership decimal appears to match the division order. Yet the final payment is lower than a quick back-of-the-envelope calculation would suggest.
Often, the answer is found in post-production deductions. These are costs associated with handling, treating, processing, transporting, or marketing oil and gas after it has been produced. Depending on the lease, the product, the state, and the way the sale is structured, some of those costs may be chargeable against a royalty and others may not be.
That makes deductions one of the most important – and most misunderstood – parts of a royalty statement. A deduction is not automatically an error, but it should not be accepted blindly either. Mineral owners should understand what is being charged, where it appears on the statement, and whether the treatment makes sense under the documents governing their interest.
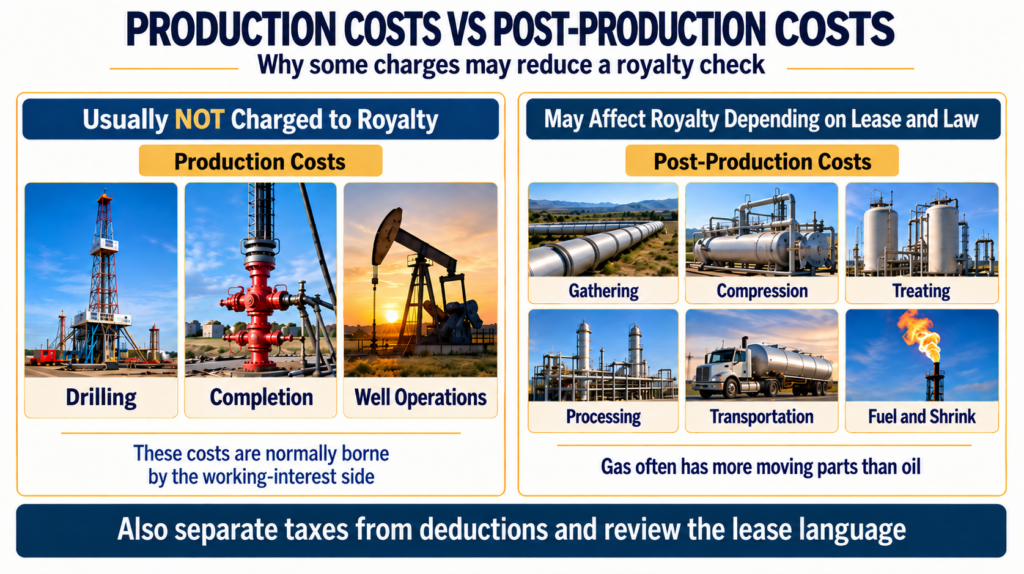
Start With the Basic Distinction: Production Costs vs. Post-Production Costs
Mineral and royalty owners often hear that their royalty is ‘cost free.’ That statement needs context. A standard royalty interest is generally not responsible for the operator’s costs of drilling the well, completing it, maintaining the wellbore, or operating the equipment necessary to bring hydrocarbons to the surface. Those are production costs and are normally borne by the working-interest side of the property.
Post-production costs begin after production and relate to getting the product from the point of production into a condition and location where it can be sold. For natural gas in particular, that can involve several steps before the gas reaches a pipeline market or downstream purchaser.
The dividing line is important because a royalty may be free of production expenses while still bearing some post-production costs. Whether that happens depends heavily on the royalty clause and applicable state law.
Common Post-Production Charges Mineral Owners May See
- Gathering: Moving oil or gas from the well or lease into a gathering system or a larger pipeline network.
- Compression: Increasing gas pressure so the product can move through gathering or transmission systems.
- Dehydration and treating: Removing water, carbon dioxide, hydrogen sulfide, or other impurities so the product meets pipeline or purchaser specifications.
- Processing: Separating natural gas liquids or otherwise processing raw gas into marketable product streams.
- Transportation: Moving the product from a gathering or processing point to a downstream market or purchaser.
- Marketing: Certain fees or costs connected with arranging the sale of production, where permitted by the governing documents and law.
- Fuel, shrink, or volume adjustments: Gas may be consumed as fuel or lose volume during processing. These items can affect the quantity credited to an owner even when they do not appear as a simple dollar deduction.
Not every operator uses the same abbreviations or statement layout. A line labeled GATH, COMP, PROC, TRANS, FUEL, or MKT may mean something different from one payor to another, so the statement legend or owner-relations department is often the best place to confirm a code.
Why Gas Royalties Often Look More Complicated Than Oil Royalties
Post-production issues are especially common with natural gas because raw gas often needs more handling between the wellhead and the final point of sale. It may pass through a gathering system, compression equipment, treating facilities, a processing plant, and then an interstate or intrastate pipeline before reaching the market.
That does not mean every gas royalty should show heavy deductions. It means there are simply more places in the chain where costs, volume adjustments, and price differentials can arise. This is one reason our recent discussion of gas-weighted minerals emphasized pipeline takeaway, processing, and market access in addition to headline natural gas prices.
Oil can have post-production costs too, including transportation, trucking, terminal fees, or marketing charges. But for many owners, gas statements tend to contain more moving parts.
Your Lease Language Is the Starting Point
When deductions appear, the first question is not simply, ‘Is this charge common?’ The better question is, ‘What does my lease say about how the royalty is valued and which costs may be considered?’
Royalty clauses may refer to terms such as market value, proceeds, amount realized, gross proceeds, net proceeds, at the well, at the point of sale, or free of cost. Those phrases can materially affect the calculation. Two owners in the same unit can therefore see different deduction treatment if they are governed by different leases.
The exact wording matters more than a single phrase pulled out of context. For example, Texas courts have repeatedly emphasized that the valuation point and the royalty clause must be read together when deciding whether post-production costs are built into the royalty calculation. Recent Texas decisions have continued to reinforce that generic ‘cost free’ wording does not necessarily mean every downstream cost is prohibited.
This is also why mineral owners should be careful with broad statements such as ‘the operator can never deduct transportation’ or ‘a no-deductions clause always fixes the problem.’ State law varies, and the full lease language controls. If the dollars are material or the clause is unclear, an oil and gas attorney may be needed to interpret it.
Do Not Confuse Post-Production Deductions With Production Taxes
Severance, production, ad valorem, or similar taxes may also reduce the amount an owner receives, but they should not automatically be lumped together with gathering or processing charges. Taxes are imposed under state or local law and may be shown separately on the revenue statement.
That distinction matters when you are reviewing a check. A payment can be lower than expected even when no post-production cost has been charged, simply because taxes were withheld. Likewise, an owner may have both taxes and post-production charges on the same statement.
When comparing deductions month to month, separate tax lines from operating or midstream-related charges so you are comparing the same categories.
A Simple Example: How a Deduction Can Change the Check
Assume an owner’s allocated share of sales revenue for the month would otherwise produce $1,000 of royalty before post-production charges and taxes. A simplified statement might show:
| Item | Illustrative Amount |
| Royalty before deductions and taxes | $1,000 |
| Gathering / compression / processing charges | -$120 |
| Production or severance taxes | -$55 |
| Illustrative net payment | $825 |
This example is only an illustration. Operators may calculate or display charges differently, and the legal question is whether the deduction or valuation method is permitted under the governing lease and law.
A Deduction May Not Always Appear as a Separate Line Item
One of the trickier parts of reviewing royalty payments is that a post-production cost may not always appear as a neat line labeled ‘deduction.’ In some arrangements, the reported price may already reflect a netback from a downstream sales point to an earlier valuation point. In other words, the effect of transportation, processing, or other costs may be embedded in the price used to calculate the royalty rather than listed afterward as a separate charge.
This is also why comparing the statement price directly with a headline benchmark such as WTI or Henry Hub can be misleading. Actual realized prices can differ because of location, quality, contract terms, basis differentials, product mix, and timing. A price difference is not automatically a hidden deduction, but a large or unexplained difference is worth asking about.
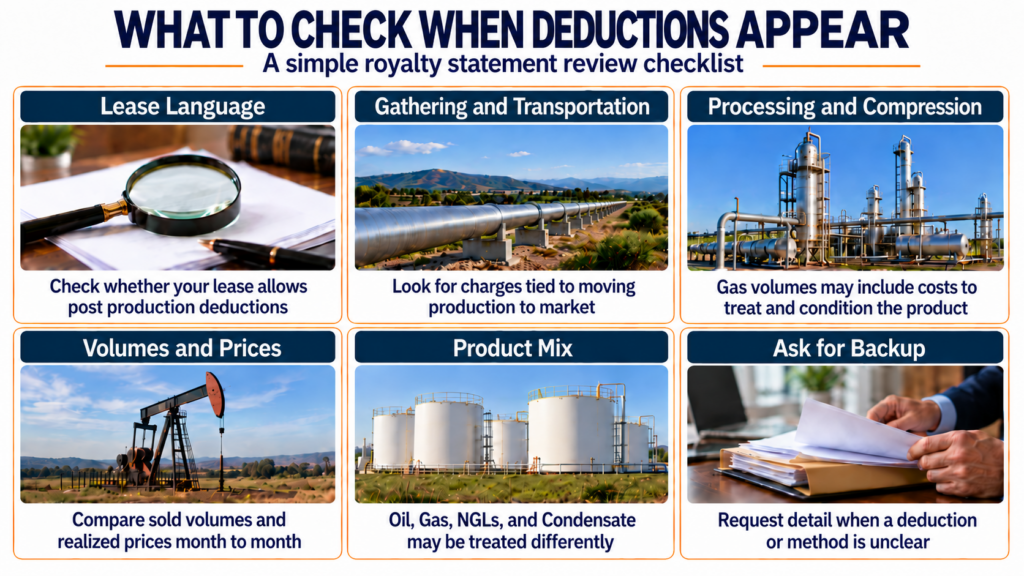
What Mineral Owners Should Check on a Revenue Statement
- Confirm the owner decimal still matches the division order or your prior statements unless there has been a known ownership, pooling, or title change.
- Separate the gross sales or gross value from the net amount used to calculate your payment.
- Identify every deduction code and determine whether it represents gathering, compression, processing, transportation, marketing, fuel, shrink, or another adjustment.
- Separate post-production charges from severance or production taxes.
- Compare deductions by product. Gas, natural gas liquids, condensate, and oil may be treated differently.
- Compare the current month with several prior months. Look for a new charge, a sudden percentage increase, or a retroactive adjustment.
- Review the lease and any amendments for royalty valuation language, no-deduction provisions, or special marketing and transportation terms.
- If the payor changed, compare the first statements from the new payor with the final statements from the prior one. A different statement format or sales arrangement can make the economics look different even when the ownership decimal stays the same.
Our earlier guide on How to Read a Revenue Statement is a useful companion to this process because deductions are only one part of the calculation. Production volumes, prices, decimal interest, prior-period adjustments, and taxes all contribute to the final check.
Red Flags That Deserve a Closer Look
A new deduction appears without an obvious explanation. Changes in purchaser, gathering contract, processing arrangement, or reporting format can create new lines, but an owner should still know what changed.
Deductions rise sharply while production and product mix appear similar. There may be a legitimate reason, but a significant change is worth reconciling.
Your lease appears to contain protective language, yet substantial deductions continue. Do not assume the operator is wrong, because wording and valuation point matter, but consider getting the clause reviewed.
The statement price is materially below what you expected and no deduction is shown. Ask whether the price reflects a netback, basis differential, quality adjustment, or another sales term.
Co-owners receive different treatment. This can be legitimate when co-owners have different leases, royalty burdens, ownership histories, or product allocations, but it is worth understanding the reason.
Large negative adjustments appear for prior months. Operators sometimes correct earlier production, pricing, taxes, or ownership allocations. Ask which production months were revised and why.
Questions to Ask the Operator or Payor
- What does each deduction code on my statement represent?
- Is the charge being deducted after my royalty is calculated, or is it reflected in the price or value used for the royalty calculation?
- What is the stated point of sale or valuation point for this product?
- Can you provide the gross price, net price, and supporting detail for the deduction?
- Are these charges specific to this well, this product, or the entire gathering or processing system?
- Did the deduction method change from prior months? If so, why?
- Are any of the negative lines actually taxes, prior-period adjustments, or ownership corrections rather than post-production costs?
- If I believe my lease restricts the charge, what documentation should I submit for review?
The goal is to move the conversation away from “Why is my check low?” and toward a specific calculation question. Owner-relations teams can usually respond more effectively when the owner identifies the well, product, production month, statement code, and exact charge in question.
Why Deductions Matter Beyond One Monthly Check
Post-production costs are not just a bookkeeping issue. They affect the net cash flow generated by an interest, which means they can also affect how a mineral or royalty asset is valued.
A buyer evaluating a producing interest will typically care about the money that actually reaches the owner, not just the headline commodity price or gross well revenue. Persistent gathering, processing, or transportation burdens can reduce net revenue. Conversely, favorable lease language or strong market access can improve the economics of an interest.
This is especially relevant for gas-weighted properties, where midstream infrastructure and regional pricing can have a meaningful effect on realized revenue. Two properties with similar production volumes can produce different owner cash flow because the lease terms, processing requirements, market access, and cost structure are different.
When It Is Worth Getting Professional Help
Many deduction questions can be answered by reviewing the statement legend and speaking with owner relations. Others are not that simple. If the issue involves a significant amount of money, unclear royalty language, multiple amendments, an inherited lease, a long history of deductions, or a disagreement over the valuation point, it may be worth having an oil and gas attorney or other qualified professional review the documents.
A land or mineral professional can also help organize the ownership, lease, unit, division-order, and payment records so the right question is being asked. The important thing is not to assume that every deduction is improper – or that every deduction is correct – without first understanding the contractual and payment setup.
How Allegiance Oil & Gas Helps Mineral Owners
At Allegiance Oil & Gas, we regularly review royalty statements, production history, lease information, ownership records, and other property data when evaluating mineral and royalty interests. Deductions are one part of that larger picture because the value of an asset depends on the net economics the owner actually receives, not just gross production.
Our role is not to provide legal advice or decide whether a particular charge is legally permissible. What we can do is help owners understand the financial side of their interest, identify the information that matters to valuation, and recognize when a payment pattern deserves a closer look.
If you are considering holding, selling, or selling only a portion of your mineral interest, understanding your net royalty income is an important place to start.
Final Thoughts
A smaller-than-expected royalty check does not automatically mean the operator made a mistake. Production volumes may have changed, the realized commodity price may differ from a headline benchmark, taxes may have been withheld, or the lease may allow certain post-production costs to be reflected in the calculation.
But mineral owners should still understand the difference between those items. Start with the revenue statement. Identify the deductions. Separate taxes from post-production charges. Compare the treatment with prior months and then return to the lease language if something does not make sense.
The most useful question is rarely simply, ‘Why was money deducted?’ It is: ‘What was deducted, how was it calculated, and what part of my lease or payment arrangement governs that treatment?’ Once those questions are answered, the royalty check usually becomes much easier to understand.
Disclaimer: This article is for general informational purposes only and is not legal, tax, accounting, or investment advice. Post-production cost treatment varies by state, lease language, product, sales arrangement, operator, and ownership history. Mineral and royalty owners should consult qualified professionals regarding their specific circumstances.